
FTP stands for Funds Transfer Pricing.
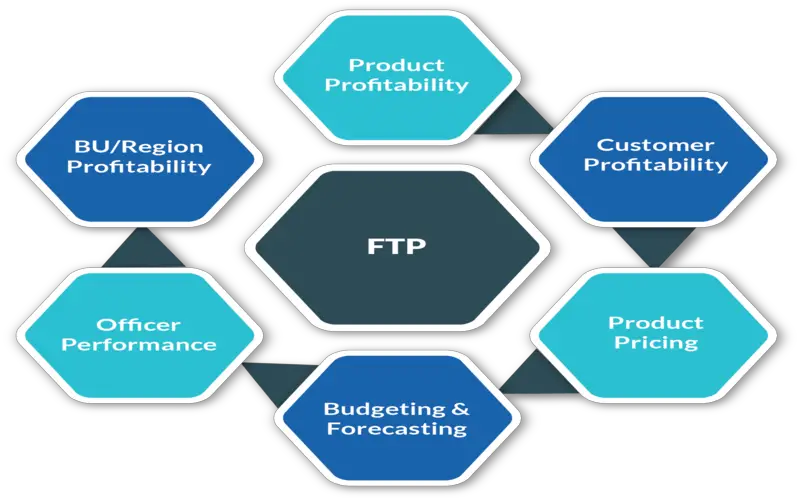
Funds Transfer Pricing (FTP) estimates how funding boosts a company’s profitability. Banks utilize FTP to assess their strengths and weaknesses. Using FTP may assist organizations in assessing product profitability, branch outlet performance, and process efficacy.
Workings of FTP
Fund transfer price is a crucial measure for banking management research and reporting. This tool helps financial institutions assess their overall and segmented profitability, such as product offers and client connections. They can also decide if holding specific branches is profitable.
A fundamental principle of FTP is that financial institutions should profit from lending and deposits. Moody says a well-designed FTP system will have a bank’s Treasury department “buy funds from the liability business unit and then sell those funds to the asset business unit at a rate that balances both the deposit and lending activity areas.”1FTP necessitates information sharing between assets and liabilities.
Analyzed alongside asset and liability management Financial institutions might assess FTP alongside other metrics like net income or net interest margin (NIM), which measures the difference between income and interest payments.
Not using FTP protocols in financial organizations’ operations poses significant risks. These concerns (not exhaustive) include:
- Losses from mispricing goods and services
- Liquidity and unhedged risks can cause business unit volatility.
- Uncertainty about product and service margins
Fund transfer pricing differs from transfer pricing, which indicates the implied prices charged by one division to another for products and services.
Methodologies for Fund Transfer Pricing
Banks employ several FTP methods. Two fundamental techniques are:
- Single-rate FTP offers a complete view of assets and liabilities by maturity. The single-rate system assigns a transfer rate to all assets and liabilities, regardless of product.
- Multi-rate FTP groups assets and liabilities by chosen attributes. The multi-rate technique gives managers a finer risk picture.
Product and maturity breakouts can use multi-rate. These breakouts may additionally incorporate the financing liquidity spread, contingent liquidity spread, credit spread, option spread, and basis spread.
Charting is essential to all FTP methods. Charting shows asset-liability shared data. Overall, it illustrates the correlation between yield-to-maturity (YTM) and time-to-maturity. Methodology and report needs can be customized for charting. Financial institutions will have an internal portal with all their high-level FTP metrics.
Most worldwide regulators do not include FTP analysis in complete bank regulatory filings.
Funds Transfer Pricing Example
Many banks examine location-based funding via FTP charting. Bank management used FTP to assess divisional fund viability. This examination considers branch deposits, loans, and consumers. Branch closure may be considered if an arm consistently underperforms or experiences considerable declines. A branch closing usually transfers accounts and resources to a nearby site.
After the 2007-2008 financial crisis, the U.S. government’s Dodd-Frank Act aimed to increase regulated liquid capital to minimize risk for central banks. Bank managers have also increased their focus on fund transfer price analysis, although advice has remained informal.
Moody’s lists the U.S. Federal Reserve’s SR16-3 letter as a prominent regulatory precedent for fund transfer pricing best practices.
Why is fund transfer pricing important for banks?
Banks and other financial entities use fund transfer pricing to assess profitability. This tool may also assess the profitability of company divisions, including products. Misspriced items and services, and volatility, might result from not having this system.
What’s the Difference Between Single-Rate and Multi-Rate FTP?
Banks utilize single-rate and multi-rate fund transfer pricing.
Single-rate FTP lets banks compare assets and liabilities. All assets and liabilities have one transfer rate under this system.
Based on attributes, multi-rate FTP groups assets and liabilities. This helps firm managers understand each group’s dangers.
How do banks profit?
What a firm or individual earns after costs is profit. Banking earnings come from several sources. The fees and services banks charge clients fuel their profitability. Loan and credit product interest also generate money.
Bottom Line
For every firm, profitability is crucial. Companies can assess their profitability using many methods. Banks and other financial organizations can use fund transfer pricing to evaluate their overall performance and that of their business divisions, goods, and services. Without this framework, financial institutions risk mispricing and volatility.
Conclusion
- Fund transfer pricing measures how funding affects corporate profitability.
- Internal analysis relies on FTP, which has various regulatory criteria for industry best practices.
- Single-rate and multi-rate approaches are fundamental internal FTP analysis systems.

