
The UK could have built a sovereign wealth fund worth around £1 trillion if revenues from North Sea oil and gas had been invested over the decades, according to new Treasury modelling.
Chancellor John Healey announced the creation of an Energy Wealth Fund on Wednesday, with £2bn in initial funding held within the National Wealth Fund. The initiative aims to invest energy-related revenues for the benefit of future generations.
The announcement has revived a long-running debate over why Britain did not follow the example of Norway, which transformed revenues from the North Sea into one of the world’s largest sovereign wealth funds.
The question is particularly significant as the UK’s national debt has reached £3 trillion for the first time.
“The proceeds of this oil and gas coming ashore now can be invested for the future generations,” Healey said.
“If we had done this when North Sea oil was first discovered in the 1980s, we’d have a British Sovereign Wealth Fund now that would be worth probably a trillion pounds.”
How Britain missed the opportunity
The £1 trillion estimate is based on internal Treasury modelling. Officials calculated what might have happened if the UK had invested its historical £200bn in North Sea oil and gas receipts, made no withdrawals and achieved growth comparable to Norway’s fund.
One government insider described Norway’s experience as proof of the value of long-term investment, saying Britain wanted to learn from the principle rather than copy the Norwegian model in its entirety.
The insider added that systematically investing the revenues could have created a substantial national asset for future generations.
The idea of establishing a British oil fund has been debated for decades. Some economists critical of former Prime Minister Margaret Thatcher’s government argue that peak oil revenues were not used to build lasting national wealth, but instead helped finance tax cuts and spending during the 1980s.
Others argue that later governments also failed to preserve the money through excessive or poorly targeted public spending.
However, Norway’s own sovereign wealth fund did not begin operating in earnest until 1996, years after North Sea oil production had started.
The idea of a UK fund has also featured in arguments made by supporters of Scottish independence and was raised by some government advisers in the 1970s.
What makes Norway’s fund so successful?
Norway has accumulated a sovereign wealth fund worth approximately $2.4 trillion by investing oil and gas revenues over the long term.
The fund is designed to preserve wealth for future generations and help finance the country’s economy as oil and gas production eventually declines.
It invests internationally and has benefited substantially from overseas investments, including shares in major US technology companies.
Norway also uses part of the fund to support public spending. Around 3% of its value is drawn down annually, helping finance roughly a fifth to a quarter of the government’s budget. Withdrawals have also helped the country respond to exceptional circumstances, including the coronavirus pandemic.
The fund’s initial investment was two billion Norwegian kroner around 30 years ago. Its value has since grown more than a thousandfold.
That experience illustrates the potential benefits of investing resource revenues over several decades rather than relying on them to finance immediate government spending.
How Britain’s new fund will be different
The UK’s Energy Wealth Fund is expected to operate differently from Norway’s model.
Norway’s fund is required to invest abroad, spreading its investments across international markets. Britain’s new fund, by contrast, is intended to support investment within the UK, particularly in green energy.
That domestic focus could make it harder for the fund to replicate Norway’s investment performance, especially given the returns Norway has achieved from overseas technology investments.
There is also a question over how much money Britain will be able to contribute in the future.
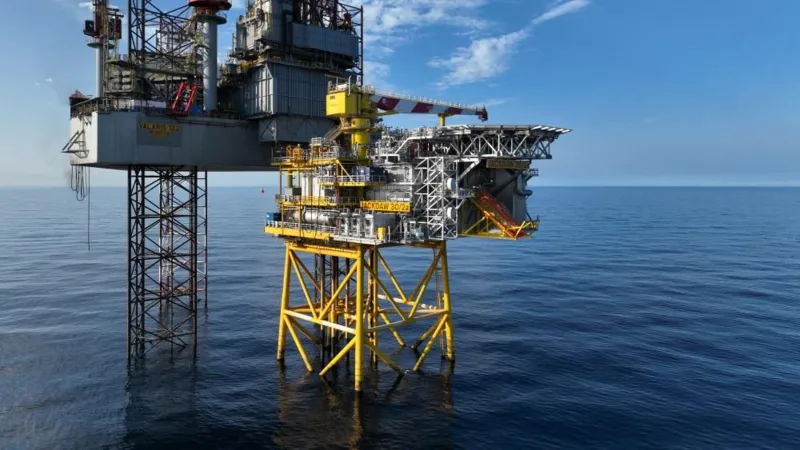
UK revenues from oil and gas taxation are forecast to decline as North Sea production falls. The rate of decline could ease somewhat following the approval of the Jackdaw gas project and extensions to existing fields.
Norway also benefits from a different ownership structure: its state retains control of its oil companies and receives a share of their profits, providing another source of income beyond taxation.
These differences mean the UK fund will face challenges that Norway’s fund did not necessarily encounter in the same way.
A long-term investment, not a quick fix
The government is not expecting the new fund’s £2bn starting capital to grow to £2 trillion within 30 years.
Instead, the announcement raises a broader question about the wealth Britain might have accumulated if it had begun investing North Sea revenues decades ago.
The new fund offers an opportunity to direct future energy income towards long-term investment, but its ultimate value will depend on the revenues available, the investments it makes and whether successive governments maintain the commitment to preserve wealth for future generations.
For now, the Treasury’s £1 trillion estimate remains a counterfactual calculation — an indication of what Britain might have built, rather than money the country can recover today.

